What you get from us on a claim
Adjusters work fast after a storm, and a roof claim is only as strong as its paperwork. Before the adjuster visit, you get a packet built for that visit:
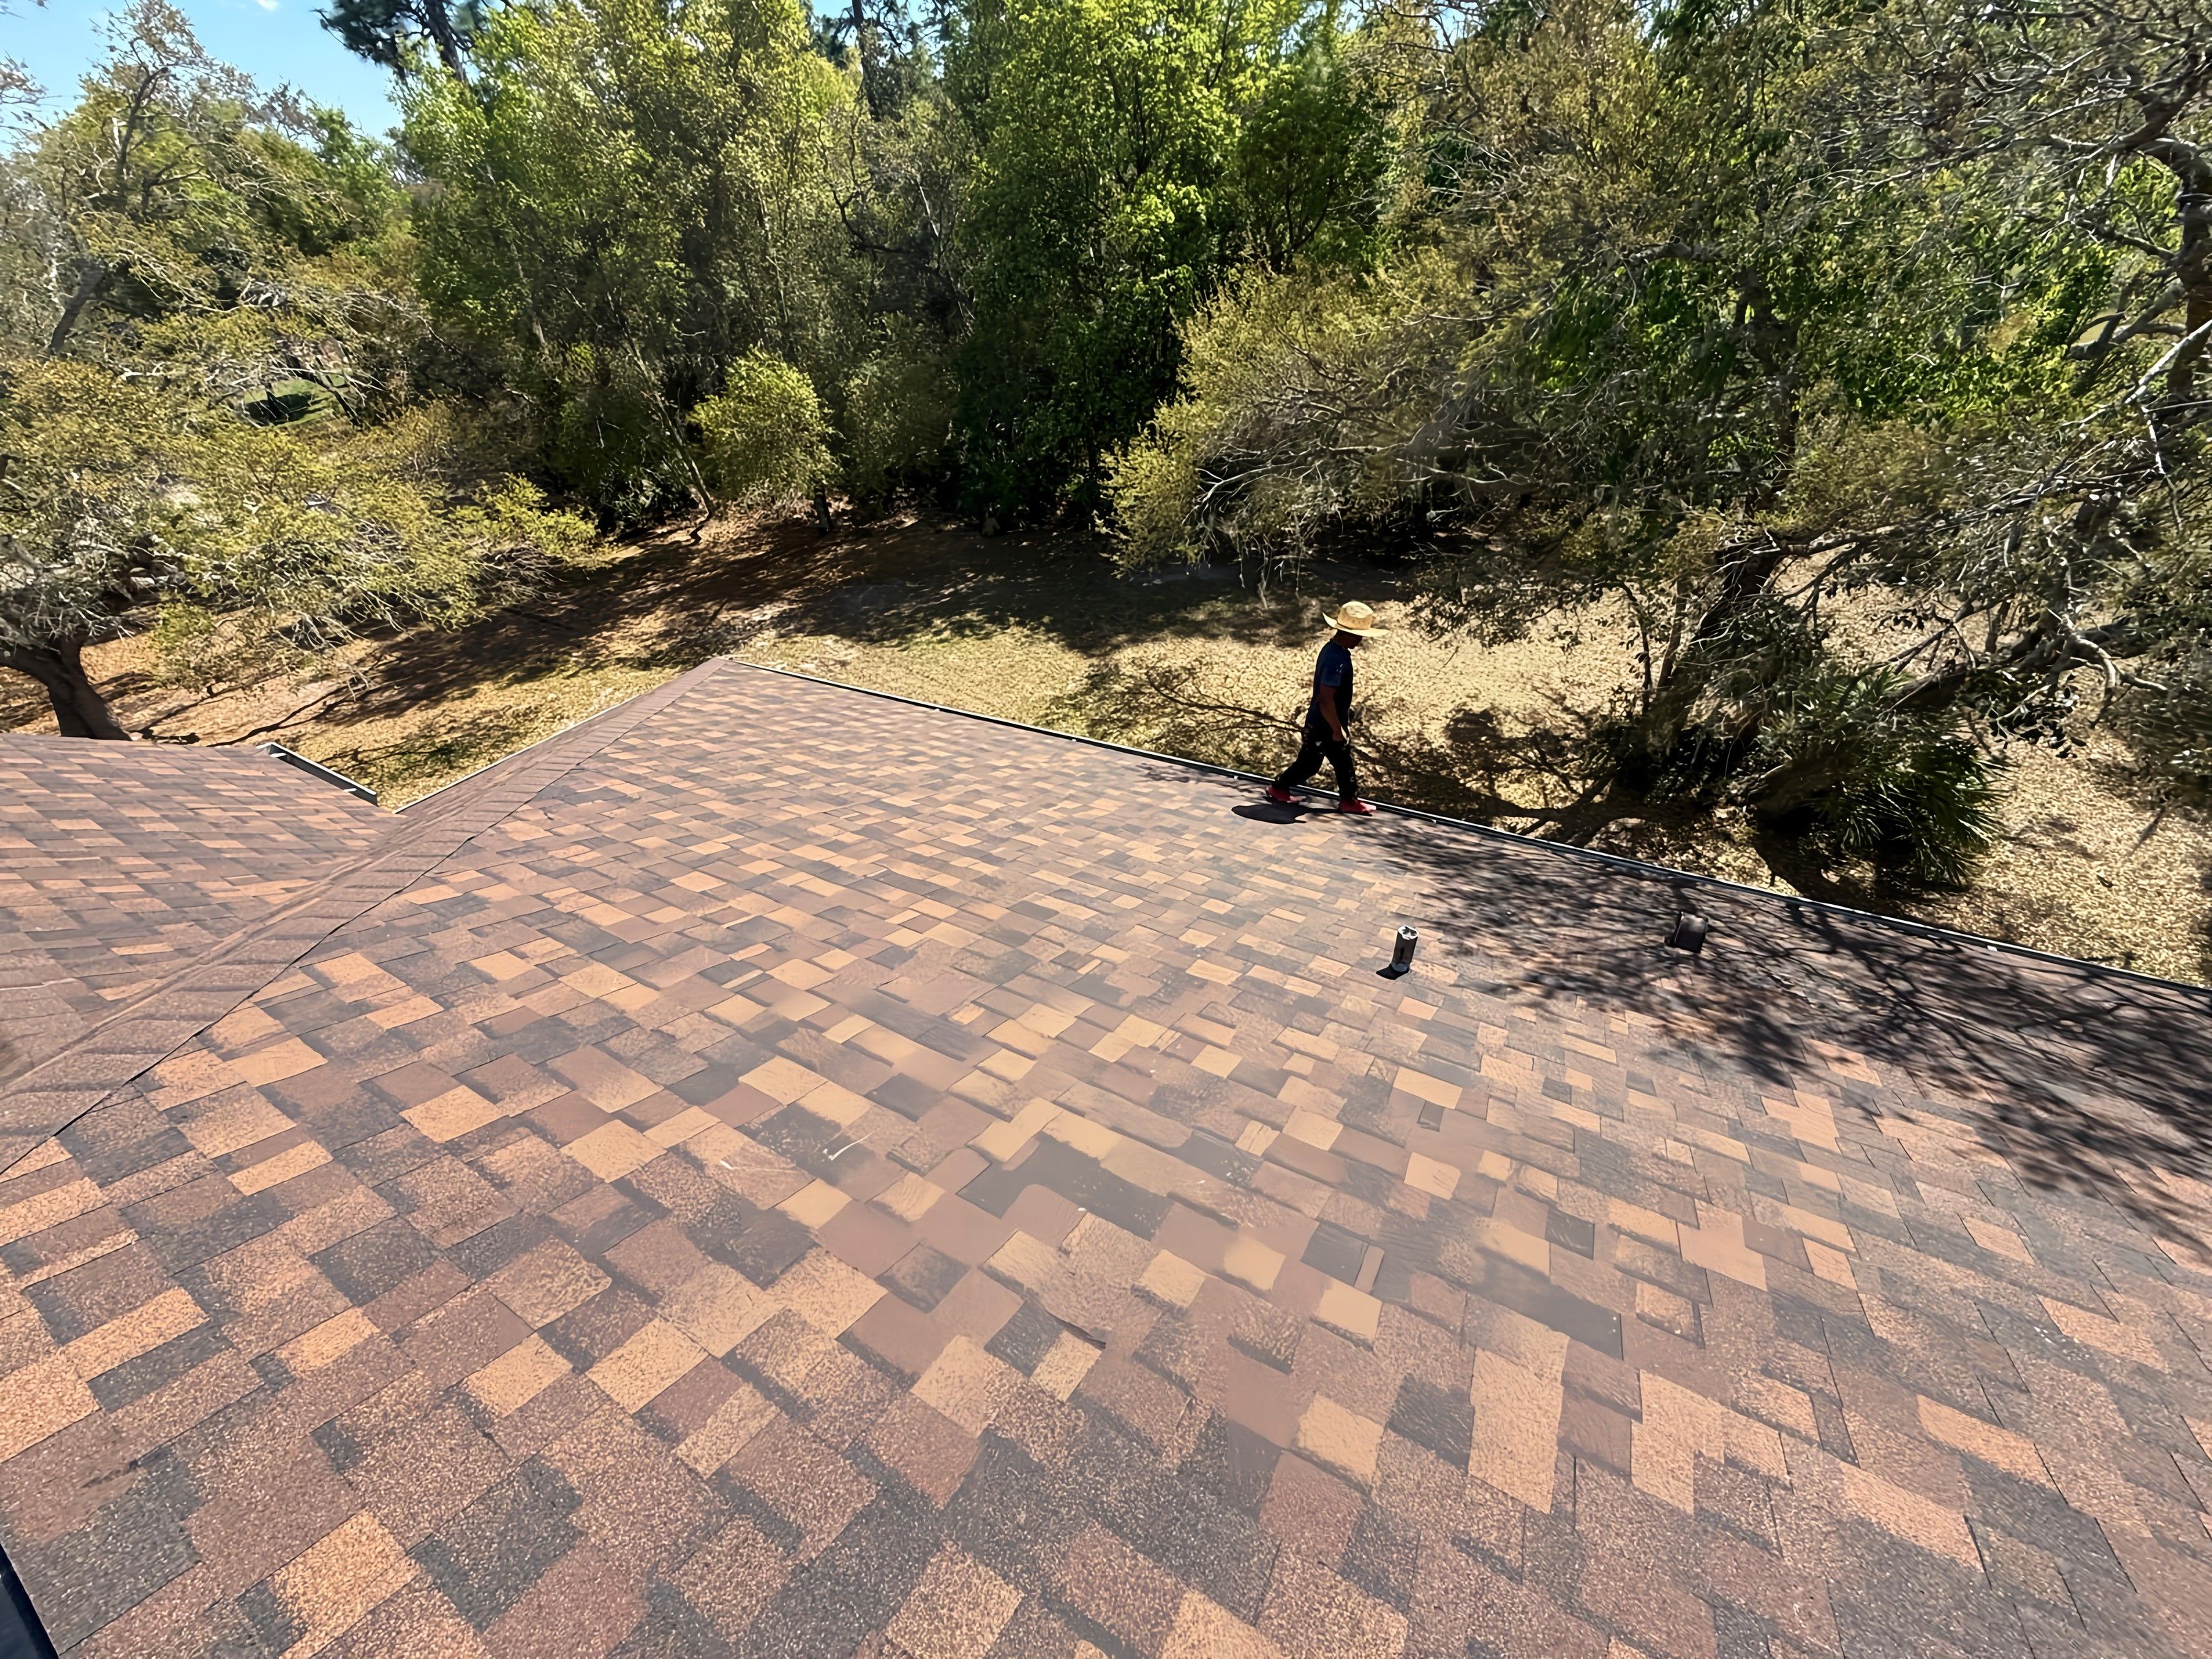
- A photo report. An overview of each slope, then close-ups of every damaged area, plus ceiling stains and attic decking from inside. Each photo is dated.
- Measurements. The roof in squares (100 sq ft each), pitch for each slope and lengths of ridge, valley and eave. When our quantities match the adjuster's, the conversation is about damage, not math. Our guide on measuring roof squares shows the method.
- An itemized estimate. Tear-off, decking, underlayment, roof covering, flashing, drip edge, vents, permit and disposal, each priced on its own line. Florida requires a good-faith itemized estimate before a contractor offers a repair agreement on a claim, and our roof quote guide explains each line.
- Code and matching notes. Where current code or a discontinued shingle affects the scope, we say so in writing. See the 25% roof rule and the roof matching law.
From first call to a finished roof
- Free inspection. We find and photograph the damage, and tarp any opening that lets water in.
- You report the claim. You contact your insurer and get a claim number. Report soon, because Florida sets deadlines on new claims.
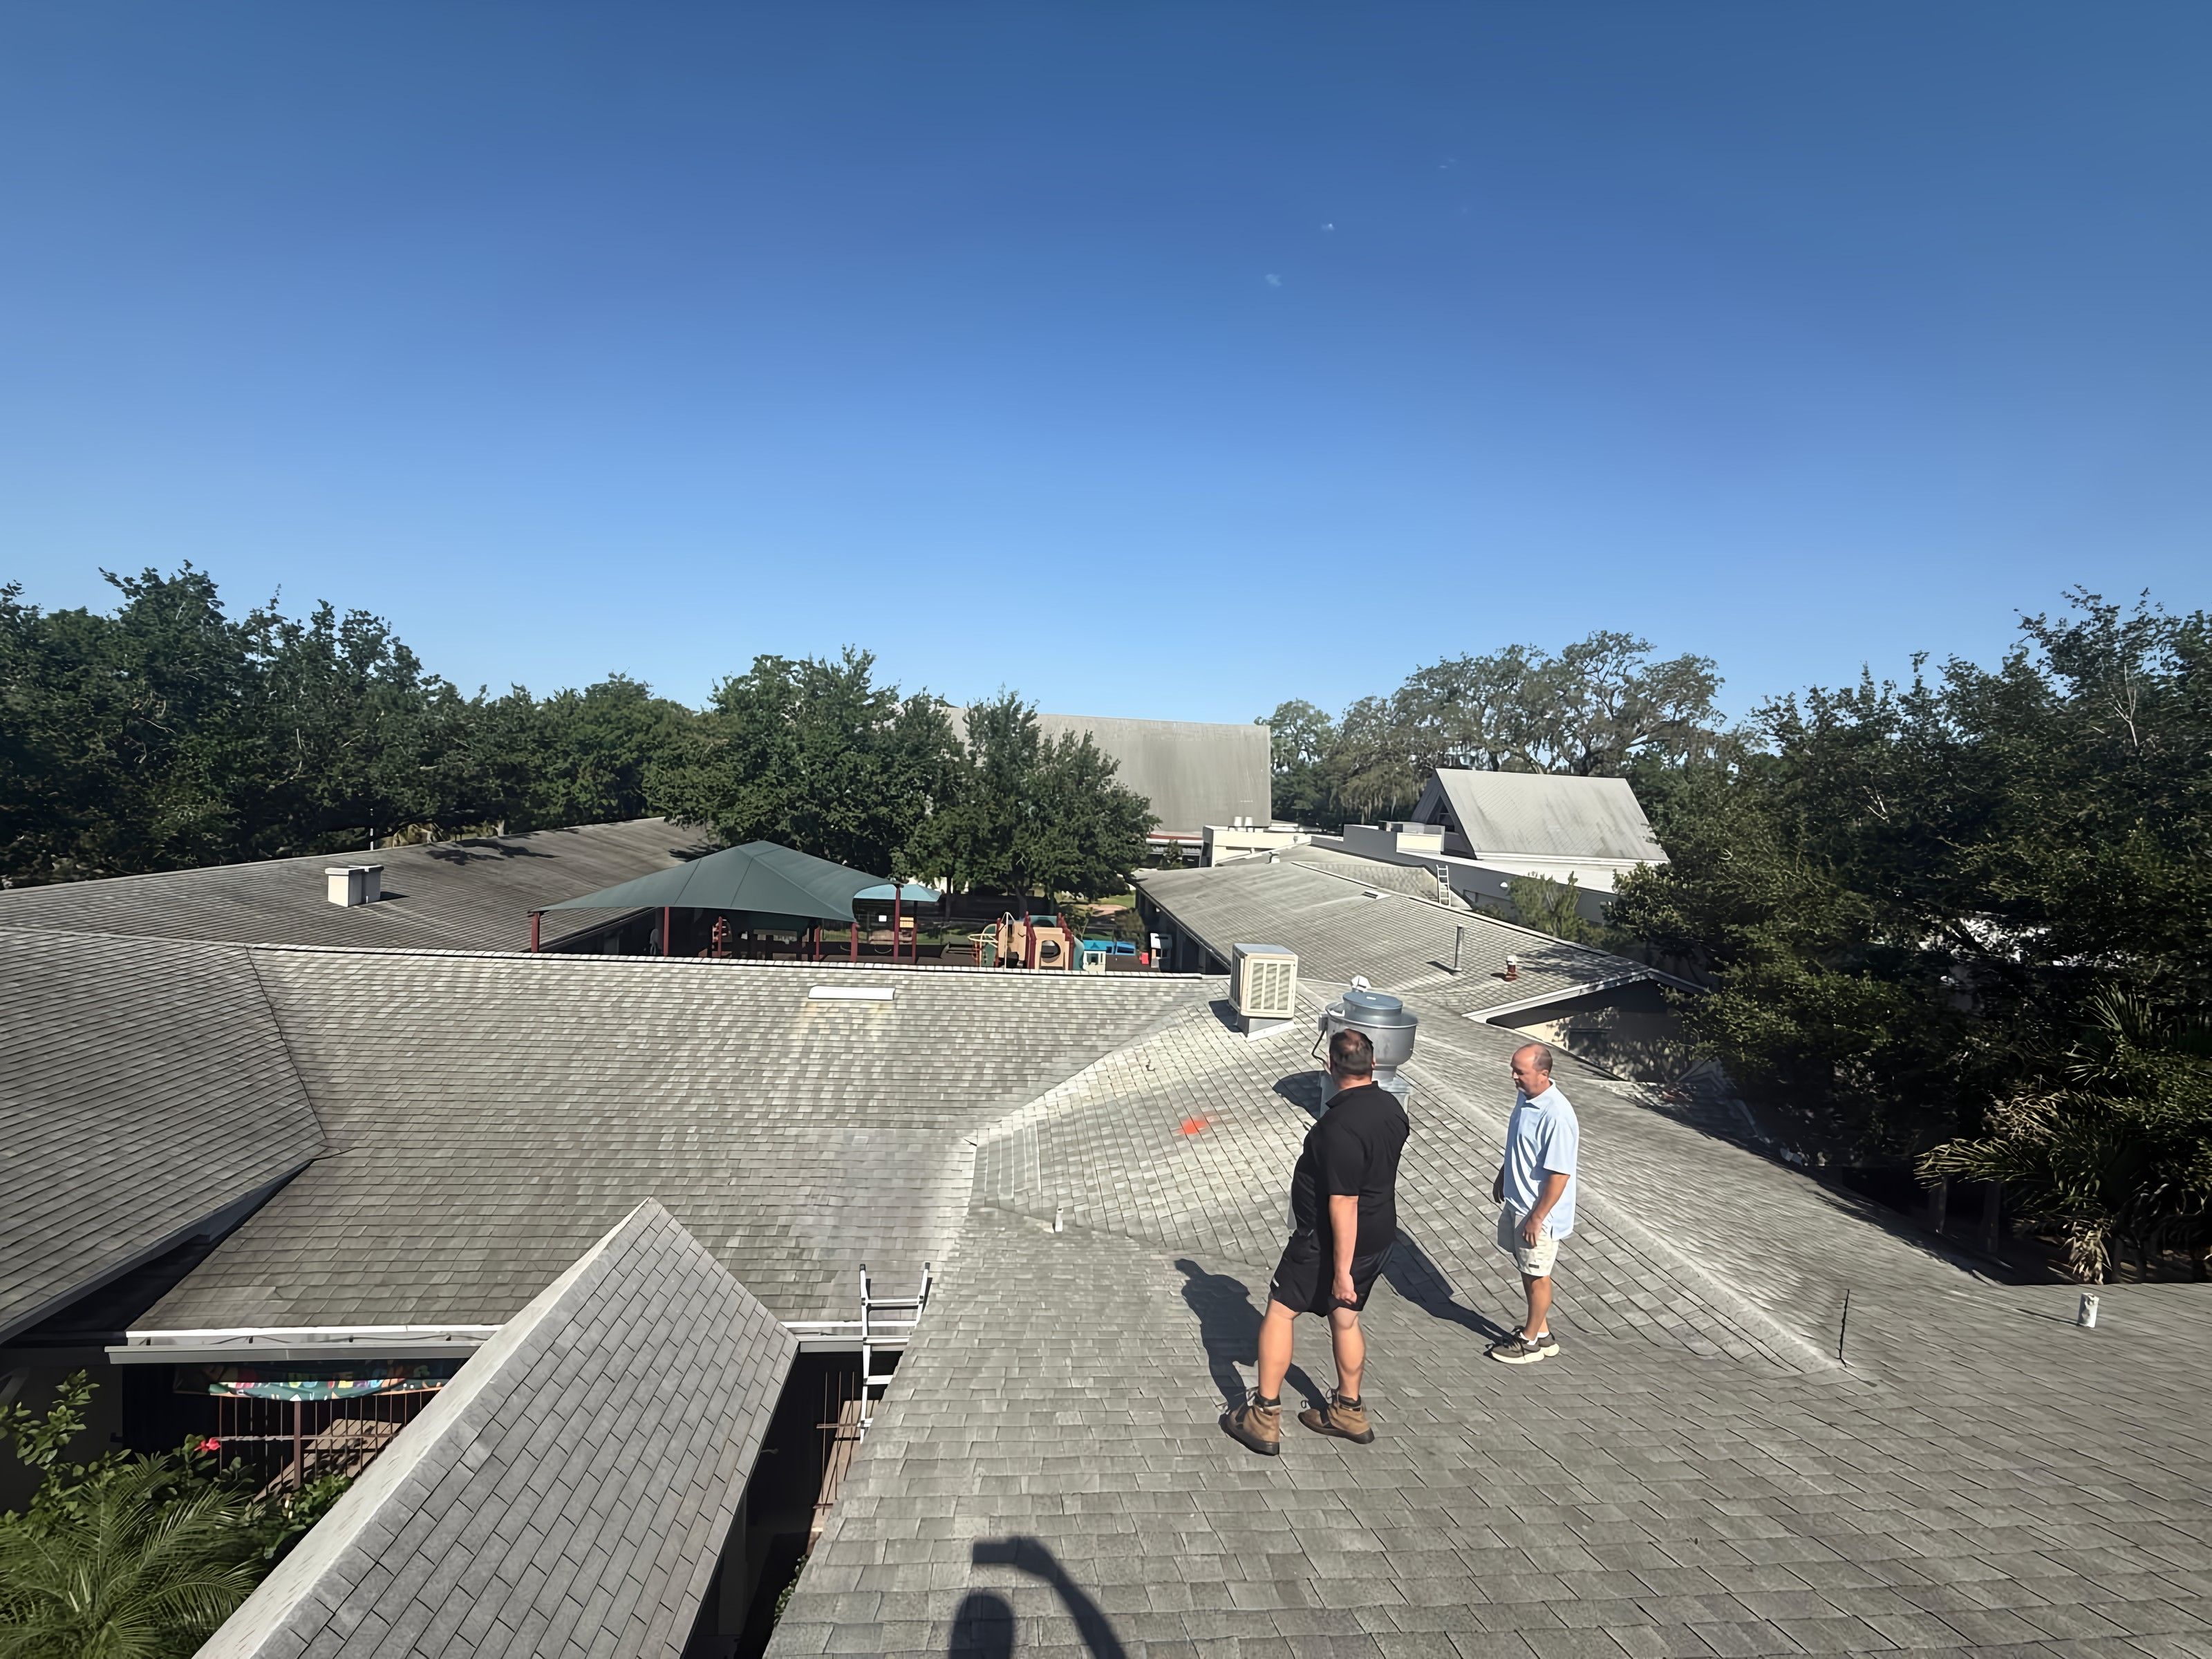
- Adjuster visit. We meet the adjuster on the roof and walk each damaged area with them.
- Estimate review. When the insurer's estimate arrives, we compare it with ours line by line and show you any gaps.
- Contract. Florida requires notices on every roof contract, including one telling you to confirm coverage with your insurer before you sign. Read them, and call your insurer if anything is unclear.
- Permit and roof. We pull the permit and do the work with our own crew.
- Closing paperwork. You get the final invoice, permit sign-off and completion photos your insurer or lender may ask for before releasing held funds.
Where claim money usually stalls
| Hold-up | What it is | Read more |
|---|---|---|
| Deductible | Your share of the loss, paid by you | Hurricane deductible guide |
| Roof payment schedule | Some policies pay a set percentage by roof age | Payment schedule guide |
| Mortgage company | Your lender co-signs the check and may release it in stages | Lender check guide |
| Denial or low offer | Wear, late reporting or damage under the deductible | Claim denial guide |
Your policy controls each of these. Your insurer or agent can tell you how yours works.
Picking a roofer for a claim job
Look up the Florida license, read reviews from before the storm and see every cost priced on paper first. Walk away from anyone who offers to cover your deductible or asks you to sign over your benefits. Ours is license CCC1326792, from an East Orlando office open since 2004. The guide to choosing a roofer has the full checklist, and what a roofer can legally do on your claim covers the rules.
Call (407) 970-9746 to book the free inspection.