Skip to content
ASSURE-U ROOFING
Get a free inspection(407) 970-9746

Storm emergencies answered 24/7.

Storm damage roof repair in Orlando, FL

  • Free storm inspection with dated photos of each damaged area
  • Emergency tarping any hour to stop water getting in
  • Line-item repair estimates to hand to your insurer
  • A roofer on site when your adjuster inspects
  • Permanent repairs or a full replacement by our own crews

Get the damage documented

Leave your number and we'll call you ASAP. We photograph every damaged area, write a line-item estimate and can meet your adjuster. Water coming in now? Call (407) 970‑9746.

We'll call you ASAP. Prefer to talk now? Call (407) 970-9746.

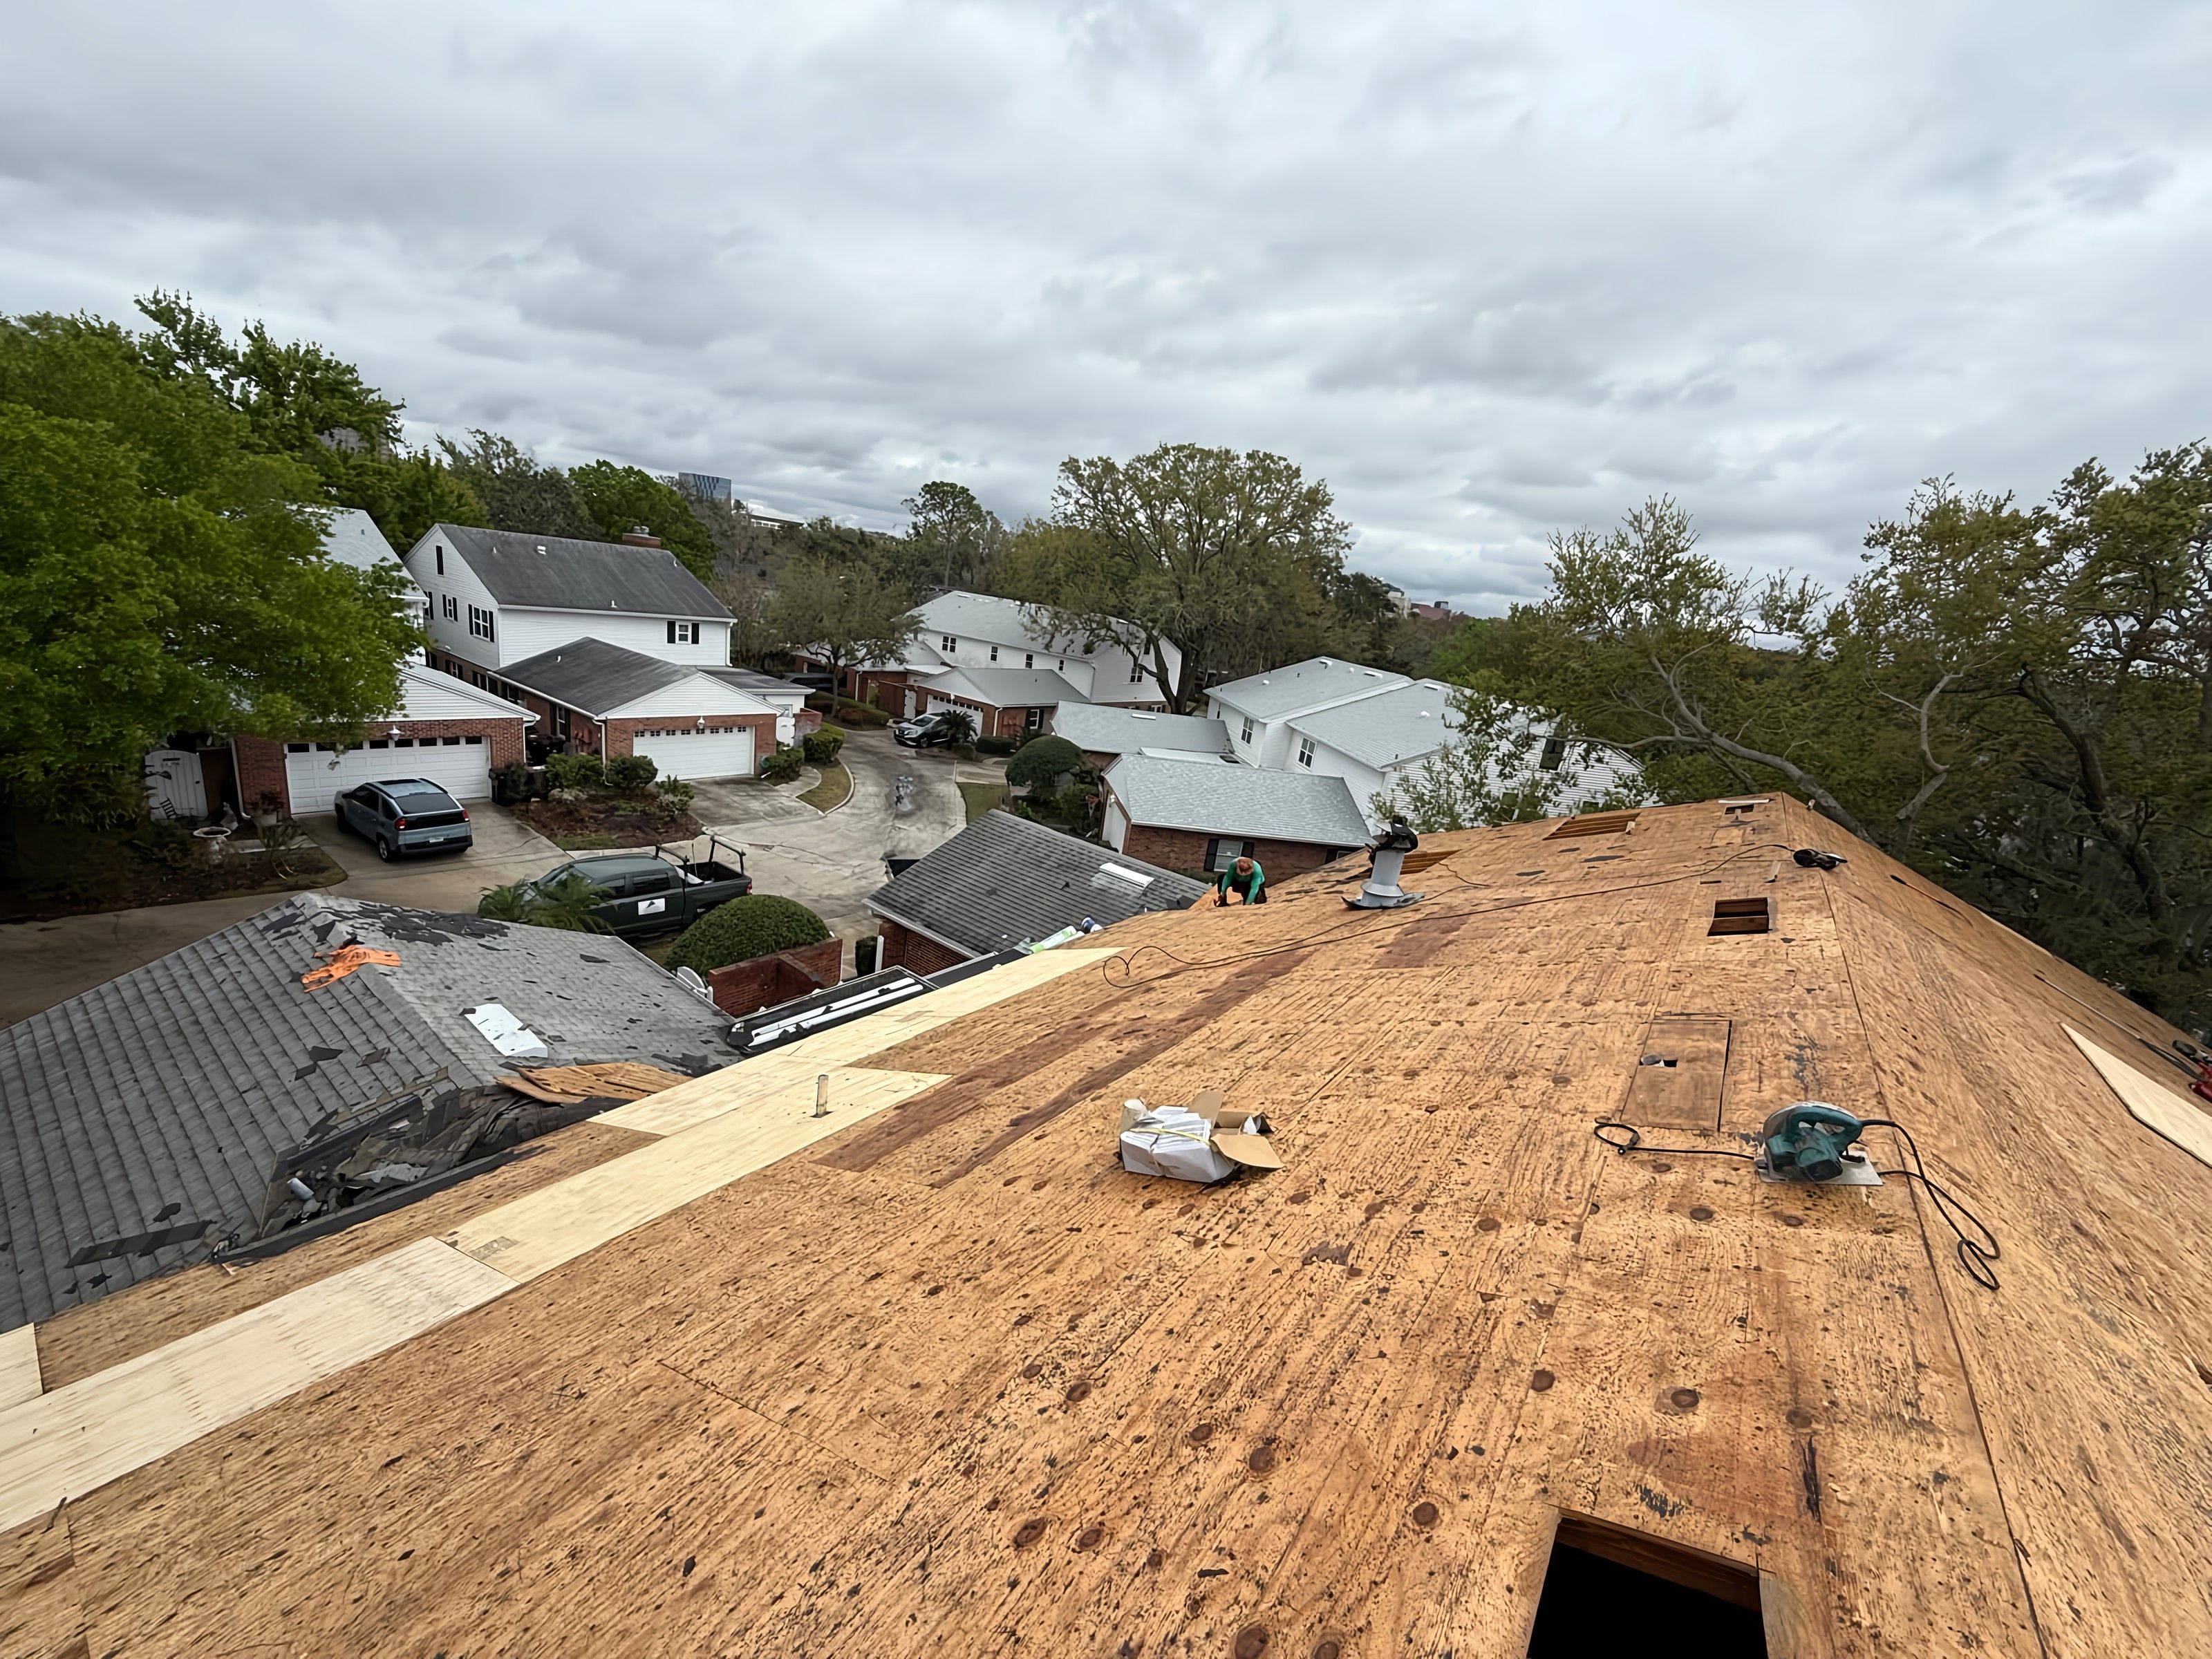
Roof stripped to the wood deck during a tear-off, with neighboring homes in view

Damage you cannot see from the lawn

Central Florida roofs get hit by hurricanes, summer squall lines, straight-line winds and the odd tornado. Much of what they leave behind is invisible from the ground. Our storm checklist covers:

  • Creased shingles. Wind can lift a shingle and break its seal without tearing it off. The crease leaks weeks later.
  • Ridge caps and edges. The perimeter and ridge take the highest wind pressure.
  • Cracked or shifted tile. Debris and uplift break tiles and expose the underlayment.
  • Bent or loose metal. Flashing, drip edge and panels pulled away from the roof.
  • Punctures. Limbs and flying objects driven through to the deck.
  • Water inside. Stained ceilings, wet insulation, drips in the attic.

Our storm damage guide walks through the first 48 hours.

Where a roofer's role ends in a claim

Florida law draws a clear line around what a roofing contractor can do in an insurance claim.

What Assure-U does What we do not do
Free inspection with dated photos Interpret your policy or coverage
Written, line-item repair estimate Negotiate your settlement
Show your adjuster each damaged spot Act as your public adjuster or attorney
Emergency tarping and permanent repairs Waive or pay your deductible

If you want someone to represent you in the claim, talk to a licensed public adjuster or an attorney.

If your homeowners policy was written January 1, 2023 or later, Florida no longer lets you assign its benefits to a contractor, so the claim generally stays between you and your insurer. Our guide on whether insurance covers roof replacement in Florida has more.

Fix the damage or replace the roof

Isolated damage can usually be repaired, typically for $1,500 to $5,000 depending on the area and whether decking or tile underlayment is involved. Damage spread across several slopes, or a storm that finishes off an already old roof, can mean a full roof replacement.

The 25% rule can matter here. In general, when more than a quarter of a roof section needs work within 12 months, that section has to meet current code. A 2022 state law carved out roofs that already meet the 2007 edition of the Florida Building Code or a newer one. Your building department and insurer decide how it applies. See the 25% rule guide.

Storm chasers

After a big storm, out-of-town crews work Orlando neighborhoods door to door. Check any roofer's Florida license, local address and reviews before you sign. Ours is CCC1326792, and we have kept an office in East Orlando since 2004. Our guide to choosing a roofer has the full checklist.

After you call

  1. Call (407) 970-9746. If water is coming in, we tarp first, day or night.
  2. Free inspection with photos of every damaged area, inside and out.
  3. Estimate and adjuster visit. You get a written estimate, and we can be there when the adjuster comes.
  4. Repair or replace with our own crews, permit pulled when required.
Questions most homeowners ask next

Storm damage questions

Still have a question? Call (407) 970-9746. A real person answers.

How long do I have to file a roof insurance claim in Florida?

Under Florida law you have one year from the date of loss to notify your insurer of a new or reopened claim, and 18 months for a supplemental claim. The legislature shortened both limits in 2022. Read your policy and report damage to your insurer or agent as soon as you safely can.

Does homeowners insurance cover hurricane roof damage in Florida?

Most Florida homeowners policies cover sudden wind and hurricane damage, usually subject to a separate hurricane deductible. Wear and old age generally are not covered. The details live in your policy, so ask your insurer or agent. We cannot interpret coverage, but we can photograph and document what the storm did.

Can my roofer handle my insurance claim for me?

No. Under Florida law a contractor cannot read your policy for you, advise you on coverage or adjust your claim without a public adjuster license. We hold no such license and we are not attorneys. What we do is inspect, photograph the damage, write a repair estimate and show the adjuster what we found.

Can a roofer pay or waive my insurance deductible in Florida?

No. Florida law prohibits contractors from offering to waive, pay or rebate your insurance deductible, and doing so can be insurance fraud. Be wary of any roofer who offers gift cards, cash or a free roof in exchange for filing a claim. The deductible is yours to pay.

Is it safe to sign with a roofer who knocks on my door after a storm?

Be careful. Ask for the Florida license number and look it up on the state DBPR site, confirm a local office address, and read reviews older than the storm. Never sign anything that hands over your claim or promises to cover your deductible. A local roofer will still be here when the tarp comes off.

Guides on storm damage

Find out what your roof needs

Ask for a free inspection. We send someone up, take photos, and tell you whether it needs a repair, a replacement or nothing yet. If it needs work, you get a written price.

Call nowFree inspection