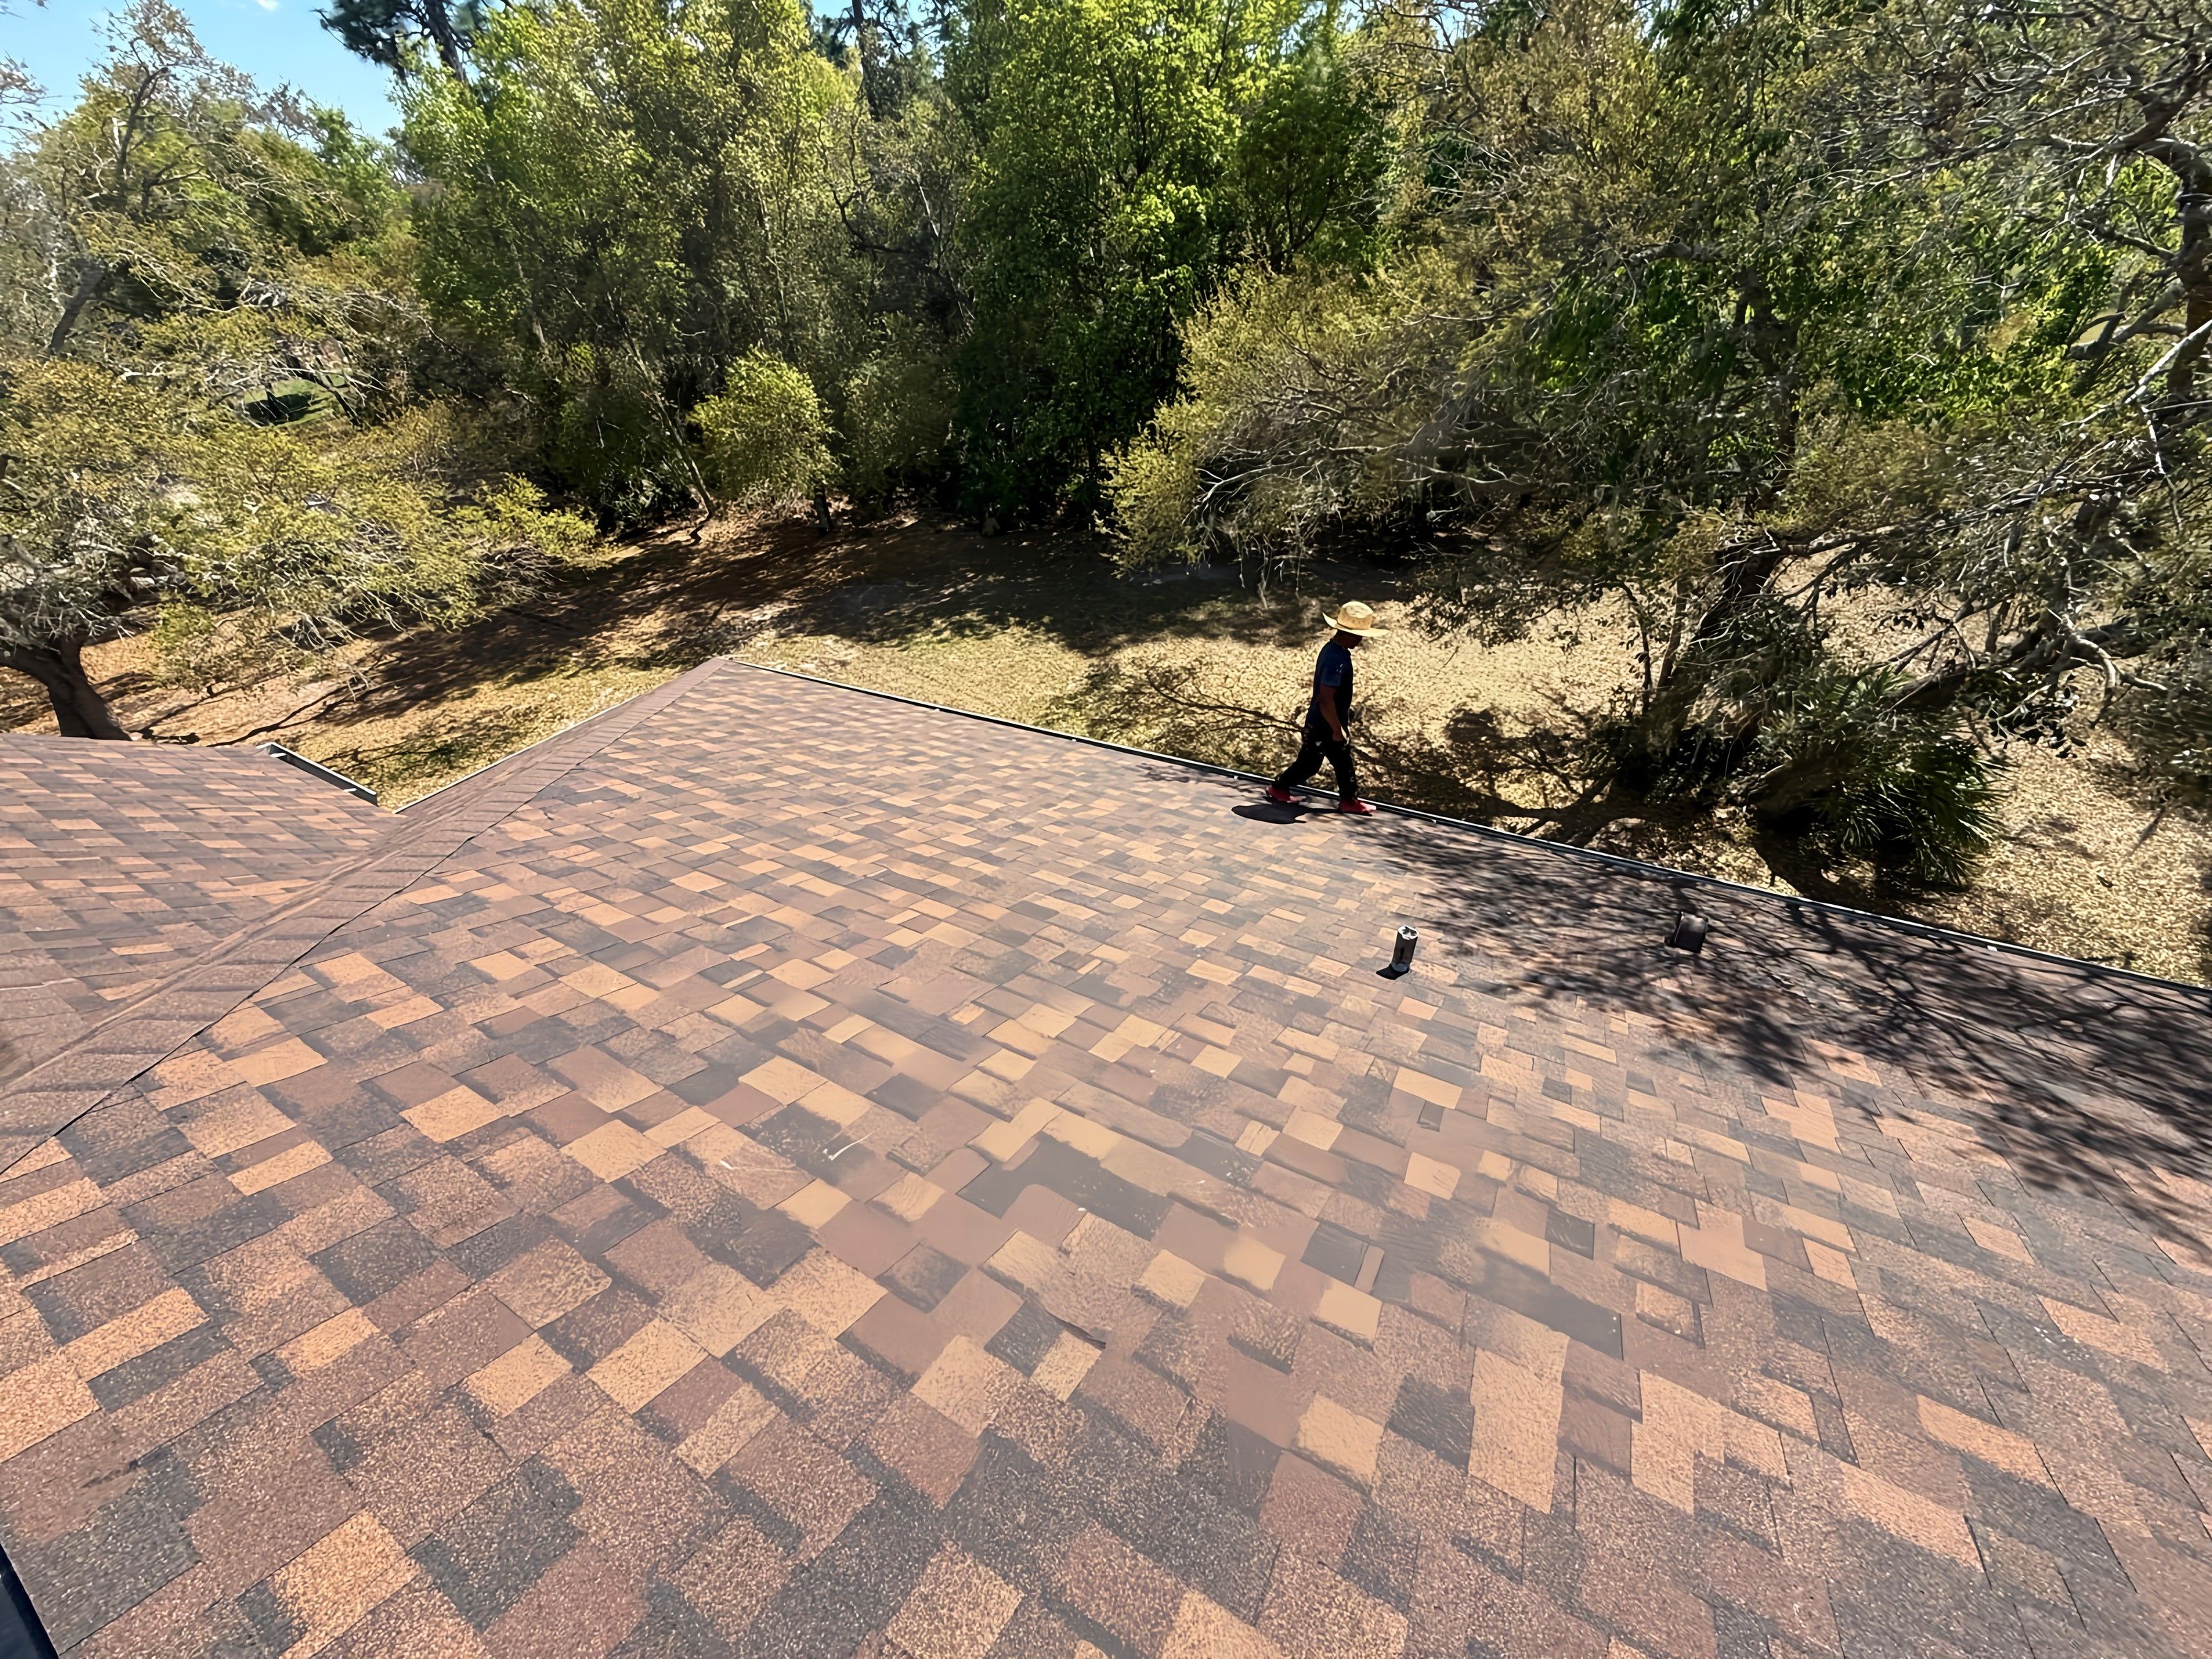
A storm tears 40 shingles off one slope. The insurer agrees to pay for the slope. The new shingles are a shade off, or the old line is discontinued, and now the roof looks patched from the street. Florida has a statute for this situation, and it is narrower than many homeowners hope.
As a contractor, we can show you the mismatch but cannot argue your policy (our guide on what roofers may do on a claim explains why). This page covers what the statute says. Applying it to your claim is for you, your insurer and, if you hire one, a licensed public adjuster or attorney.
What does Florida's matching law say?
The law is Florida Statutes section 626.9744, titled "Claim settlement practices relating to property insurance." It dates to 2004. It applies when a homeowners policy adjusts and settles first-party losses based on repair or replacement cost, unless the policy says otherwise.
The matching rule is subsection (2). In plain terms, when a loss requires replacing items and the replaced items do not match in quality, color or size, the insurer must make reasonable repairs or replacement of items in adjoining areas.
What can the insurer consider?
The statute lets the insurer weigh several factors in deciding how far the repairs go:
- The cost of repairing or replacing the items
- How much uniformity can be achieved without replacing more
- The remaining useful life of the undamaged portion
- Other relevant factors
That list is why matching claims get argued. A 3-year-old roof with a discontinued shingle and a 22-year-old roof with the same problem can come out differently, because the remaining life of the undamaged part is on the list.
What the matching law does and doesn't promise
| The statute does | The statute does not |
|---|---|
| Require reasonable repairs or replacement in adjoining areas when replaced items don't match | Guarantee a full roof replacement |
| Cover quality, color and size | Define exactly what an adjoining area is on a roof |
| Apply to repair or replacement cost settlements | Override a policy that provides otherwise |
| Let the insurer weigh cost and remaining life | Make the insurer a warrantor of the repairs |
The last row is in the statute itself. Subsection (3) says the section does not make the insurer a warrantor of the repairs it pays for.
What counts as an adjoining area on a roof?
The statute does not define it. On a roof with several planes, it could mean the damaged slope plus slopes that meet it, or the whole roof face visible from one side. Because the statute leaves it open, the answer depends on the facts of each roof and the terms of your policy.
What you can control is the evidence. Clear photos of every slope, the shingle or tile brand and color, and proof that the product is discontinued all help the adjuster see the mismatch for themselves.
How do I show my shingles can't be matched?
- Identify the product. Look for a leftover bundle wrapper, the original invoice or your roofing contract. A roofer can also inspect the installed shingles or tiles.
- Check availability. Ask the manufacturer or a supplier whether the product and color are still made. Get the answer in writing if you can.
- Photograph side by side. If a sample of the closest current product is available, photograph it next to your installed roofing in daylight.
- Send it to your adjuster. Put the photos and the availability answer in writing to your insurer, and keep a copy.
We cannot negotiate your claim, but we can give you an itemized estimate, photos and the product details so you have what you need. A free roof inspection is a good place to start.
What if I disagree with the insurer's matching decision?
Florida law gives you a few tools.
- The reason, in writing. Florida Statutes section 627.70131 makes the insurer put the policy basis for a full or partial denial on paper. A payment below its own detailed estimate needs a written reason for the gap too.
- A copy of the estimate. The same statute requires the insurer to send you any detailed estimate of the loss within 7 days after its adjuster generates it.
- Free mediation. Florida Statutes section 627.7015 creates the state mediation program, and in most cases the insurer covers the mediator's fee.
- Someone licensed to argue it. Public adjusters and attorneys can take on your policy and claim. Roofers cannot.
For questions about the process itself, Florida's Department of Financial Services takes calls at 1-877-693-5236.
Does the 25 percent rule change the matching question?
It can make it moot. On a roof that predates the 2007 code, a repair big enough to cross a quarter of a section can force that section to be redone to code anyway, and then matching stops mattering. That code cost is a law and ordinance item. Our 25% roof rule guide explains when that happens.
For a broader view of roof claims, see why Florida roof claims get denied and what to do after roof storm damage. Have a mismatched repair or a discontinued shingle? Our storm damage repair service starts with photos of every slope and the product details your adjuster will ask for.